It is not uncommon for us to take instruction to add a third party’s interest onto an existing policy. However, any noted interest on an insurance policy needs to be noted correctly to ensure the policy reacts in the intended purpose, in the event of a claim. Therefore, we need to ensure that the policy matches the contract, so we will often ask for details as to what the interested party require.
The below identifies the various options available:
Note of interest – There isn’t a defined legal position on a note of interest and often, note of interest clauses can either cover very little or can cover extremely wide. Because of this uncertainty, we look to ensure we understand what a person’s interest is before noting it on the policy, to protect our clients, as well as their partner’s interest.
Joint insured – A Joint insured is a common request, meaning that more than one party is insured on a policy. This is often requested on a Contractors All Risk policy where you have two or more parties interested in the same contract. We can only add a joint insured whereby each insured has a financial interest in the risk, meaning in the event of a material loss, they would make a loss – which the insurance is required to cover. However, a joint insurance policy can have its flaws, as a breach in contract and one insured party could invalidate the policy to all other insured parties. Joint insurance is used, therefore, where there is a mutual interest such as a husband and wife insuring their home.
First Loss Payee – This means that those noted will get paid first for their loss in the event of a claim, in line with the amounts shown on the schedule. For example, the policy could react that any small claims of up to £25,000 would be paid to the policyholder – anything above that £25,000 would be paid to the funder until they have exhausted their interest. So, in this example, if there was a £1,000,000 loan then they would only be able to claim up to their £1,000,000 investment and for claims which went above this, the difference would be paid to the policyholder.
Hot tub accidents triple in lockdown
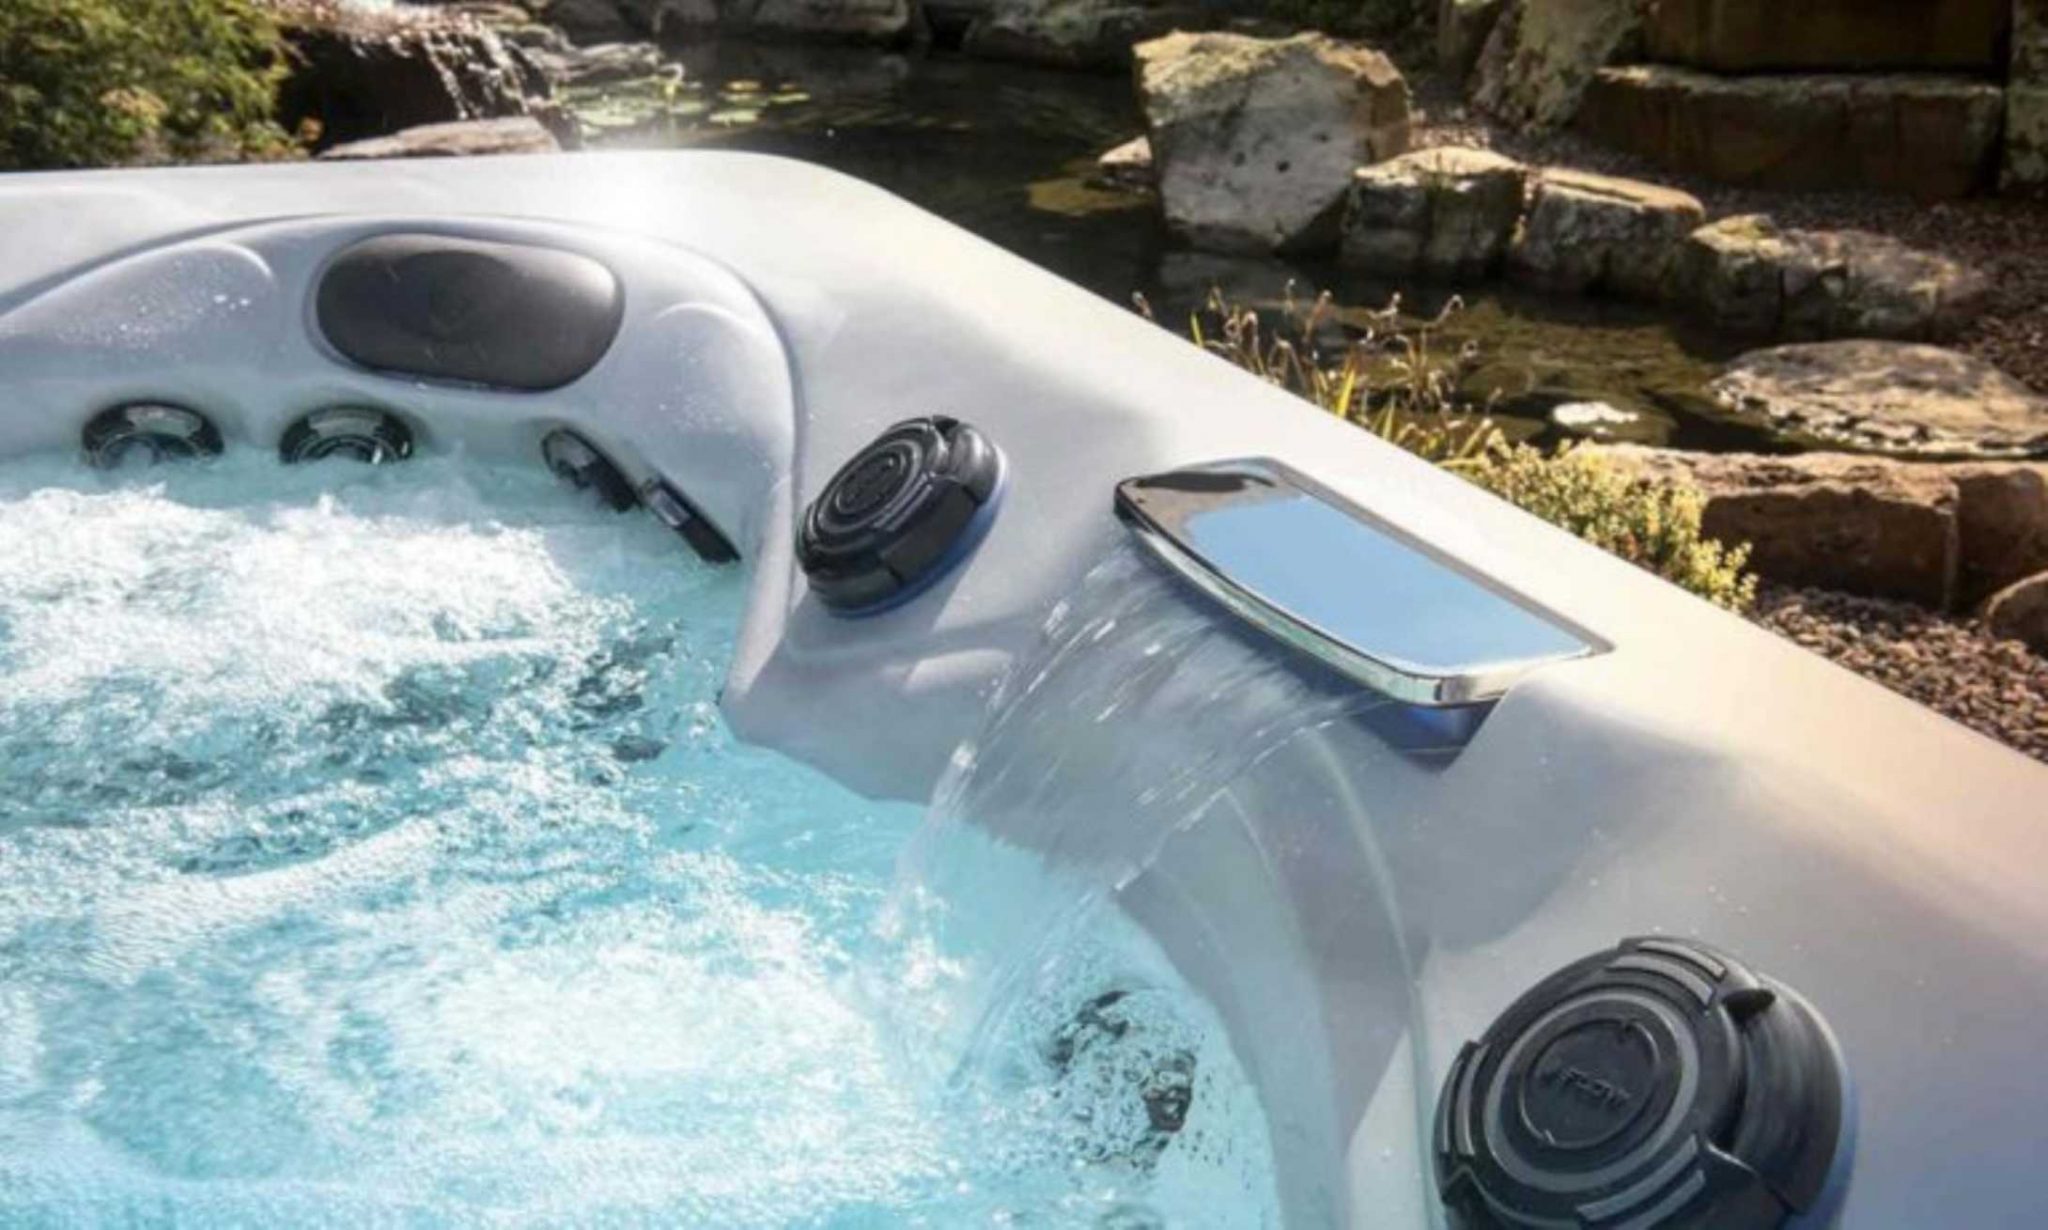
Home insurance claims involving hot tubs bubbled over last year as people spent more time in their gardens during lockdown, an insurer has said. Insurers said there had been a 188% year-on-year increase in accidental damage claims for hot tubs in 2020.
Claims they accepted include a grass strimmer bursting an inflatable tub and an engagement ring ripping a lining.
The high-ticket items rocketed in popularity in 2020 as more people spent summer in the UK.
Last June, shopping platform eBay reported sales of hot tubs had increased by nearly five times. And, stock on Argos’s website remains limited, where hot tubs can cost up to £6,439.
But parasols falling into tubs have also caused customers trouble, as have birds pecking holes in their covers.
The insurer added that accidental damage claims for items dropped in, or knocked off the side of, hot tubs in the UK have also increased in recent years. Mobile phones topped the list of items that took the plunge.
The insurers also saw a small number of claims for stolen hot tubs. In many cases, deflated, out-of-use, spas were stolen from garages and outbuildings.
Many people bought hot tubs in 2020, while others took their spas out of storage, so they could enjoy holidays at home. Unfortunately this appears to have led to all manner of mishaps, both with the hot tubs themselves and items dropped in them.